
Listen to the latest episode of Credit Exchange with Lisa Lee
Published in London & New York
10 Queen Street Place, London
1345 Avenue of the Americas, New York
Creditflux is an
company
© Creditflux Ltd 2026. All rights reserved. Available by subscription only.


Analysis New managers
Newcomers shape global CLO market
by Kathryn Gaw
A barrage of new firms have entered the European CLO market – with more to come – fuelling fears about the availability of capital, loan supply and talent to sustain the rapid growth
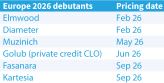
Muzinich, Elmwood, Diameter, Kartesia, Fasanara, Golub – these are the six new managers that have entered the European CLO market in the year to date, in what promises to be the busiest ever year for new entrants. But this recent influx is creating fundamental shifts in the market and raising concerns about the availability of capital, loan supply and talent.
Within the coming months, more debut prints are expected. The names run from SCOR to Eiffel, Ardian, Corinthia, Park Square and Davidson Kempner, as well as rumoured incoming strategies from the likes of Oak Hill Advisers, AGL, TCW, Nuveen and Squarepoint.
If every firm with hopes for a new CLO management business succeeds in its aspirations, the count of continental managers could grow by 25%, according to Creditflux calculations. By next year, about 100 managers could be actively issuing CLOs in Europe. This compares with 156 active broadly syndicated loan (BSL) CLO managers in the US, an eye-popping figure given that the European market is but a fraction of the size of the US one.

Too many managers
“I think there are probably a lot more managers than one would reasonably expect in Europe as is,” says Edwin Wilches, a managing director and co-head of PGIM Credit’s securitised products team.
The surge is fuelling concerns about the availability of the capital, loan supply and talent in Europe that is required to sustain the rapid growth of this market. Creditflux is aware of at least four potential new managers that have opted to hold off on launching their strategies for now, amid fears of overcrowding. “The market doesn’t feel good right now,” said one of these firms. “There are too many managers and too few deals out there.”
Every year brings a scattering of new entrants to the CLO space, but in Europe, this year feels different. In 2024, three new managers printed their first deals, in 2025 it was four, and by the third quarter of 2026 it is six and counting. By the time the year is over, debut prints by debut managers will represent a significant percentage of European CLO issuance volumes, helping to propel the market to another record-breaking year.
Investors want the right team
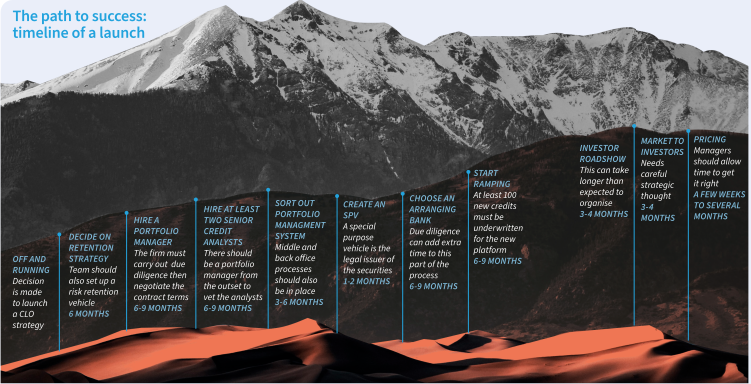
It takes about two years to launch a CLO strategy, from the moment that the decision is made until the day of pricing. The current batch of new entrants probably began this process in late 2024 or early 2025, when the low-yield environment in the US was already causing CLO equity and tranche investors to cast their eyes further afield.
“Most new entrants today are acting on decisions made several months ago,” says Richard Jacquet, CEO of CLO tranche investor ZenCap Asset Management. “The business case was solid: mid-teens equity returns, stable AUM and a natural diversification for credit and private debt managers.”
Since then, the landscape has changed somewhat – arbitrage remains stretched with equity returns now in the high single digits on the primary market, while default risks have risen and loan supply has been constrained. Yet investor appetite remains strong for the right management team.


With many platforms seeking to launch in Europe, access to recurring CLO equity capital will be critical
Michael Htun
Head of CLOs and structured credit, Kartesia
Jacquet is one of the investors who is prepared to back a new entrant, with the caveat that he is looking for a good team track record, adequate staffing and a long-term commitment to the product. “The new manager pickup can more than compensate for the lower liquidity,” he added.
Indeed, two of the most recent debutant issues – Fasanara and Kartesia – priced their triple As at Euribor plus 129bps, representing a 5bp premium against the market benchmark.
“Of course, we priced a bit wider than established managers, because it’s the first one,” says Till Schweizer, the managing director and portfolio manager at Fasanara Capital. “And also, we don’t have the backing of a large institution or a US hedge fund. But I think investors really like our story. They liked my experience, and they also liked the team we built at Fasanara with the experienced credit analysts. They’ve been very receptive and supportive.”
Access to equity is crucial
Prior to joining Fasanara, Schweizer spent almost 18 years at Partners Group, managing its CLO strategy. Kartesia has tapped its own head of CLOs and structured credit, Michael Htun, to oversee its CLO programme, and he has acknowledged that the firm’s 13-year track record of investing in CLO equity enabled it to raise a significant proportion of its dedicated CLO equity capital from third-party investors.
“With many platforms seeking to launch in Europe, access to recurring CLO equity capital will be critical,” says Htun. “Our analysis of successful and less successful launches suggests that this is the single most important factor. Without visibility over future deployment, it is difficult to demonstrate the ability to issue repeatedly. This can affect sponsor relationships, loan allocations, talent recruitment and, ultimately, performance.”
Access to equity has been named by many as the number one challenge to new managers. Typically, a new manager needs to have about EUR 200m of equity, either in the form of captive equity or through the backing of a sponsor. Most European new entrants are opting for captive equity, which has substantially narrowed the field of potential contenders to either US-based CLO managers or existing European direct lenders and private credit shops.
“Investors are looking for well-established and well-resourced platforms with the ability to scale and a commitment to building a durable European lending platform,” says Tyler Wallace, managing director for European broadly syndicated loans at Golub Capital. “US managers entering the European market with a long track record of actively managing CLOs are well positioned to meet increasing investor demand for these products.”
Golub is one of the best-known private credit specialists in the US and debuted into the European market in June with a private credit CLO. Its first BSL deal is expected to be priced in the coming months.
Creditflux has spoken to a range of longstanding CLO investors, many of whom have echoed Jacquet’s view that they would be happy to back a debut issuer as long as they had confidence in the portfolio manager and the analyst team. However, some European and US investors maintain a strict policy of never investing in a first deal, making that initial print all the more challenging. “Some of them have said: ‘Please come back for the second one, that one we can do,’” says Schweizer.
Choosing the right arranging bank is also proving to be a challenge. There are a limited number of banks available to European portfolio managers, and competition is intense among debutants. One portfolio manager told Creditflux that the top European arranging banks are limiting themselves to working with just two new managers per year, which has resulted in an audition-like process among managers who understand the value of a top-tier arranger. A new manager needs an arranging bank that has the capacity to organise up to 100 meetings. That means working with one of the top three arranging banks – BNP Paribas, Bank of America and Jefferies – and convincing them to work with you. In parallel with the rise of new CLO managers in Europe, there has also been a rush of new arrangers entering this space, ready to fill the gap in supply.
Shifts in the market
This is just one of the ways in which the influx of new managers is creating fundamental shifts in the European CLO market. Market participants expect to see even more pronounced dispersion in the market in the year ahead, as these newcomers vie for the same pools of capital as incumbents, and investors start to reallocate their funds.
Talent churn is also expected to continue. Experienced portfolio managers and senior analysts are in high demand. Some have solved this hiring problem by bringing people over to Europe from the US market, but these markets are still quite different and there is a sense that a new European platform needs a European lead.
Some investors have said: ‘Please come back for the second one, that one we can do’
Till Schweizer
Managing director, Fasanara Capital
These portfolio managers also want to know that the company they are joining has long-term staying power. Schweizer says that one of the key reasons why he joined Fasanara was because Fasanara had its own equity capital and an existing European base. “I also really liked the culture – it’s an entrepreneurial firm,” he says. “I have lots of freedom to build out a team here. And it’s a very colloquial atmosphere, which I thought would be a great place to start out and build a new platform.”
Analysts are almost more in demand than portfolio managers. It is now widely accepted across the market that AI can cover the day-to-day responsibilities of a junior analyst, but senior analysts are still required to oversee this work and do more intensive credit picking and underwriting. But there is a clear shortage of people with this level of experience, and delays in this area of the hiring process are known to be slowing down some new entrant plans.
Despite these hiring difficulties, one incoming manager told Creditflux that they feel extremely lucky to be setting up a team now and not a year ago, because they are able to embed the latest AI from day one and make use of the most up-to-date technology, which is becoming a key part of the investor pitch for many new entrants.
New entrants, fresh start
In a way, these new entrants can represent a fresh start for CLO investors, who can invest in a brand-new portfolio with a more modern structure. The use of AI at the junior analyst level can more than halve the time it takes to analyse deals on the primary market, and new entrants are able to offer this speed advantage immediately, whereas incumbent managers may need months to reframe their legacy processes in the AI world.
New managers also offer lower triple C exposure, at a time when the market is voicing concerns about the 2028 maturity wall. These managers are also coming into the market at a time when multicurrency deals and hybrid BSL/PC CLOs have already moved the needle in terms of deal innovation. With these blueprints already in existence, they are well placed to be able to deliver more bespoke offerings to investors.
“We are seeing increasing demand for comprehensive financing solutions across direct lending, high yield and broadly syndicated loans, and for managers that can work across multiple jurisdictions and currencies,” says Wallace.
The near-term opportunity set is particularly compelling
Tyler Wallace
Managing director for European broadly syndicated loans, Golub Capital
This is an asset class that has clearly matured, with more than a decade of stable performance under the CLO 2.0 regime, and proven experience of resilience in the face of macroeconomic volatility.
Meanwhile, the investor base has continued to grow, more recently with the rise of CLO ETFs, which have allowed high-net-worth individuals to access the market for the first time. Forthcoming EU regulations promise to open the market up to more insurance capital in the near future, which would be transformative for this space. But in the short to medium term, loan supply anxieties persist.
“The clearest constraint is limited loan supply,” says Htun. “Growth in the European CLO market has significantly outpaced net new loan issuance, creating a strong technical backdrop. However, we do not expect this imbalance to persist indefinitely. Europe has substantial financing needs, and CLOs are becoming an increasingly important source of funding.”
Another record-breaking year
One CLO investor told Creditflux that the number of new entrants is simply not sustainable unless there is a significant increase in the volume of the loan market.
This problem may soon be resolved. The pipeline appears to be robust, with several managers and analysts estimating that EUR 40bn of M&A will be coming to the market by the end of the year, which will result in more CLOs being priced. At the time of writing, 2026 is expected to be another record-breaking year of issuance for the European CLO market.
“Compared with recent years, we believe the near-term opportunity set is particularly compelling and should remain supportive through at least early 2027,” says Wallace. “In our view, the combination of heightened primary market activity and periodic market volatility is creating attractive entry points for active CLO managers.”
Market View
Where are the new entrants coming from?
For years, there has been speculation that a raft of US managers are bringing their businesses to Europe to diversify their portfolios and meet investor demand.
This year, a trio of US firms – Elmwood, Diameter and Muzinich – priced their first European BSL deals. Golub Capital joined the market in June with a Euro-denominated private credit CLO. But other long-rumoured US entrants appear to have cooled on their plans. Sixth Street was thought to be close to launching a European strategy, but a spokesperson said it hasn’t even begun the hiring process yet. Octagon has spoken about starting a European business for years but told Creditflux that it has no news to share about a European presence.
Instead, the next cohort appears to be coming from Europe. Paris-based private credit specialist Eiffel is expected to print its first deal in the first half of 2027, having hired former AXA IM portfolio manager Xavier Boucher and Eiffel veteran François Gignoux to lead the CLO strategy.
French insurer SCOR has tasked its structured credit head Rémy Chupin to lead its European CLO strategy, and is also expected to enter the market in the coming months. In July, French investment firm Ardian appointed Carlyle’s head of European liquid credit Stuart MacKenzie to lead its new European CLO business, business. In February, Park Square announced the launch of its European CLO platform, although the firm has yet to price its first deal.
These European moves reflect both the growing interest in European private credit CLOs and the understanding that the US is a very different place to do business. Local regulations make running a European shop more admin-intensive and an understanding of the cultures and banking practices can smooth the path for newer players.
