
Listen to the latest episode of Credit Exchange with Lisa Lee
Published in London & New York
10 Queen Street Place, London
1345 Avenue of the Americas, New York
Creditflux is an
company
© Creditflux Ltd 2026. All rights reserved. Available by subscription only.


Events Awards
Hayfin sees dispersion in debt markets
by Lisa Lee
We spoke to Marc Chowrimootoo, co-head of direct lending for private credit at Hayfin Capital Management, which won Private Credit Lender of the Year at the European Private Equity Awards
Lisa Lee: Congrats on Hayfin’s win. What do you think about credit markets now?
Marc Chowrimootoo: If you reflect on the syndicated loan and high-yield bond market, you see that volatility in the news, you see it in earnings, you see it in the trading levels of some of those larger names in particular. There are also some idiosyncratic risks, which we’re seeing on a name-by-name basis. The other theme I would add to that list is dispersion. We are still seeing deals getting done at attractive levels, as well as those that have been pulled. So the market is bifurcating a little bit into the haves and have-nots, or at least, those that are getting disproportionately punished.
I would highlight a couple of things as it relates to the private credit market and direct lending in particular. There’s always a lag between what’s happening in the public markets and what happens in private credit. We’ve seen that time and time again.
We’re also at the part of the year where a lot of our peers are worried about deployment. Deployment has been challenging for much of this year. If you think about M&A volumes this year, whilst we had a bit of a pickup in Q3, Q1 and Q2 were reasonably weak, and a lot of peers haven’t deployed that much coming into this Q4 period. On the borrower side, there’s always a bit of a race to get deals done by the end of the year, and those deals tend to generate more intense demand from people who haven’t deployed. Naturally this has an artificial impact on price, documentation, and leverage because there’s an intensified level of competition for high- and sometimes even medium-quality assets as we go into year-end that you don’t typically see throughout the year.
We go into the Q4 period having deployed about EUR 8bn in direct lending through the last 12 months and we don’t feel under any real pressure to deploy.
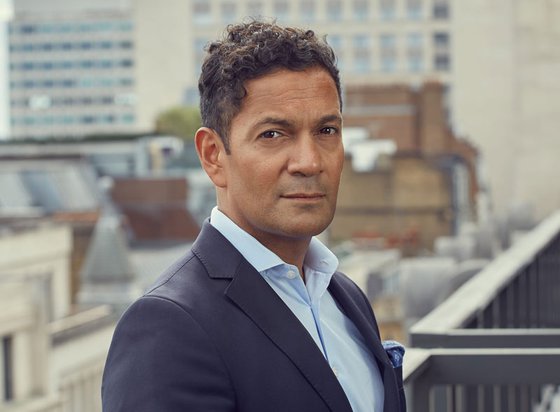

The market is bifurcating into the haves and have-nots
Marc Chowrimootoo
Co-head of direct lending
Hayfin Capital Management
LL: Are you seeing signs already in the direct lending market, or is it something you’re bracing for?
MC: We’re seeing some dispersion in credit quality. For assets of high quality, terms haven’t really changed, pricing hasn’t really changed, documentation hasn’t really changed. Where credit quality is second- or third-tier, the sort of level that we wouldn’t play in, there are always marginal buyers who are prepared to do it for a price. So there is a little bit of a spread widening for those assets.
LL: What areas are you bullish on, given the more volatile period?
MC: We’re seeing a lot of activity in the asset-light financial services sector, such as wealth management, and in the TICC (testing and inspection) space. There are segments of the broader professional services space where we we’re seeing a lot of high-quality companies come through. But I wouldn’t say there’s any real new pockets of deployment.
We saw a pickup in activity in Q3, Q4 is going to be a little bit more muted. But, there still is a wall of private capital that needs to be put to work from an ownership perspective. In fact, if you talk to some of the more successful GPs on the private equity side, actually they are reasonably bullish in terms of the capital that has returned this year and the outlook going into 2027.
LL: And how was the fundraising environment in the past year?
MC: Our experience is that institutional investors understand the value of private credit as part of a much broader diversified portfolio. They understand the strategic value that the asset class brings to their own allocations. They understand the value of Europe relative to the US. And so we haven’t seen any material reduction in appetite for European direct lending in particular.
What I would say, though, is that there is more scrutiny in manager selection, and the flight to quality is much more pronounced now than it’s ever been.
LL: Corporate earnings have been strong so far, but are you seeing anything in your portfolio that worries you?
MC: Despite this stress and volatility, the portfolio is holding up well. Our trajectory in terms of number of watchlist names continues to fall from the peak in 2023.
No matter how vigilant you are, if you manage a large portfolio of investments some of them will experience stress. But the question is: are you going to have 10% of your book experiencing some level of stress, or are you going to have 20, 30, 40% of your names on watchlist? This is where manager selection matters most.
